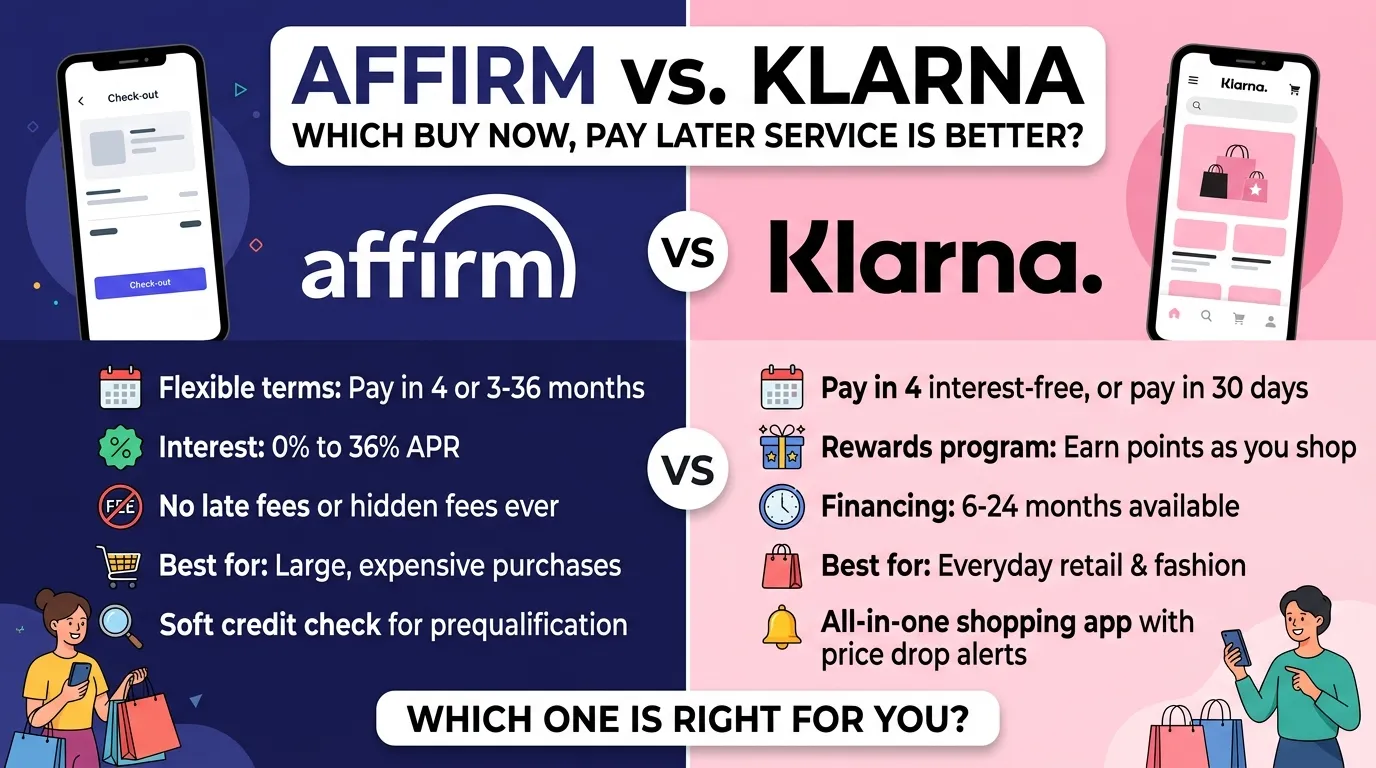
Affirm and Klarna both let you buy now and pay later, but they differ in payment plans, interest charges, approval rules, and shopping features.
Imagine you want to buy a new laptop. You have enough money to pay part of the cost today, but you would rather spread the rest over time. You look online and find two options: Affirm and Klarna. Both may help you split the cost into smaller payments. But which one should you choose?
When people search for affirm or klarna, they often want to know which service is cheaper, easier to use, or better for online shopping. They may also wonder whether both services offer the same payment options.
Affirm and Klarna are known as Buy Now, Pay Later (BNPL) services. They let eligible shoppers pay for certain purchases over time instead of paying the full amount at once. However, their terms can differ by store, country, purchase, and customer.
Pronunciation
Word
US pronunciation
UK pronunciation
Affirm
uh-FURM
uh-FURM
Klarna
KLAHR-nuh
KLAH-nuh
Pronunciation can vary slightly by speaker. Affirm sounds like “a firm,” while Klarna sounds roughly like “clar-nuh.”
Read more about:https://gatherword.com/roach-or-beetle/
Difference Between Affirm and Klarna
Both services help people spread out payments. However, they offer different plans and features.
1. Payment Plans
Affirm offers short payment plans and longer monthly plans. Klarna also offers short plans and monthly financing in supported markets.
- Example 1: You split a $200 purchase into four payments with Affirm, if eligible.
- Example 2: You choose Klarna Pay in 4 to split a $200 purchase into four payments, if eligible.
2. Interest Charges
Some Affirm plans have no interest. Other plans may charge interest. Klarna also offers interest-free plans and some financing plans with interest.
- Example 1: You select an eligible 0% Affirm plan.
- Example 2: You select an eligible interest-free Klarna plan.
Always check the total cost before you agree.
3. Late Fees
Affirm says it does not charge late fees. Klarna may charge late fees on some US payment plans if you miss payments. Rules vary by product and location.
- Example 1: You miss an Affirm payment and contact its support team to arrange payment.
- Example 2: You miss a Klarna payment and may face a late fee under your plan’s terms.
4. Payment Schedule
Both services offer plans that divide a purchase into smaller payments. The exact dates depend on the plan.
- Example 1: You pay an Affirm installment every two weeks.
- Example 2: You pay a Klarna Pay in 4 installment every two weeks.
5. Shopping Options
Affirm offers payment plans at participating stores and other payment methods, such as a virtual card in supported markets. Klarna offers its app, participating store checkouts, and other payment options in supported markets.
- Example 1: You choose Affirm when a store offers it at checkout.
- Example 2: You choose Klarna when it appears as a payment option.
6. Larger Purchases
Affirm offers longer monthly plans for some purchases. Klarna also offers monthly financing for eligible purchases. Approval and rates depend on the plan.
- Example 1: You use an eligible Affirm plan to pay for a laptop over several months.
- Example 2: You use an eligible Klarna financing plan to pay for furniture over time.
7. Approval
Neither service guarantees approval for every purchase.
- Example 1: Affirm approves one purchase but offers no plan for another.
- Example 2: Klarna approves your order today but declines a later order.
8. Shopping Apps
Both services have apps that help users shop and manage payments.
- Example 1: You open the Affirm app to check an upcoming payment.
- Example 2: You open the Klarna app to review your orders and payment dates.
9. Payment Flexibility
Both services offer different options, but the choices shown to you may not be the same.
- Example 1: Affirm offers you a short plan and a monthly plan for a purchase.
- Example 2: Klarna offers you Pay in 4 and Pay in 30 days for an eligible order.
10. Availability
Affirm and Klarna are not available to every shopper in every country. Their services also depend on local rules and participating stores.
- Example 1: A US shopper finds Affirm at an eligible online store.
- Example 2: A UK shopper sees Klarna’s Pay in 3 option at checkout.
Which is better? Compare the exact plans offered to you. The best choice is often the one with the lowest total cost and a payment schedule you can manage.
Nature and Behaviour of Affirm and Klarna
Nature of Affirm
Affirm is a payment service that offers installment plans for eligible purchases. Some plans are interest-free, while others charge interest. Its US website states that it does not charge late fees.
Its main features include:
- Short and long payment plans.
- Clear payment amounts before you accept a plan.
- Options for shopping at participating stores.
- No late fees under its stated fee policy.
Nature of Klarna
Klarna is a payment service that gives eligible shoppers several ways to pay. These may include paying now, paying later, splitting a purchase into installments, or using monthly financing. Available options depend on the country and purchase.
Its main features include:
- Pay in 4 in the US, where offered.
- Pay in 3 in the UK, where offered.
- Pay in 30 days in supported markets.
- An app for shopping and payment management.
Why People Get Confused About Affirm and Klarna
They may also appear at the same online stores. Both can show a payment amount at checkout, and both may offer interest-free plans.
The key difference is that their payment rules are not always the same. One may offer a plan that the other does not. Fees, interest, approval, and payment dates can also differ. The shopper should compare both offers instead of choosing by brand name alone.
The Origin of Affirm and Klarna
The Origin of Affirm
Affirm was founded in 2012 in the United States. It became known for offering payment plans at online checkout. Its goal is to give shoppers clear terms before they agree to pay over time.
Over time, the company added more ways to pay and expanded its merchant partnerships.
The Origin of Klarna
Klarna was founded in Sweden in 2005. It grew from an online payment business into a global shopping and payment service. It later expanded into the US and other markets.
Today, both companies are known for Buy Now, Pay Later services. Their products continue to change as they enter new markets and add payment features.
British vs American English
Affirm and Klarna are brand names, not British or American spelling variants. Their names do not change between the two forms of English.
The main difference is in the payment options available in each market.
- US example: A shopper may see Klarna Pay in 4, with four payments made every two weeks.
- UK example: A shopper may see Klarna Pay in 3, with three payments under the terms offered in the UK.
For Affirm, available plans and eligibility also depend on the market.
If you write for a US audience, use terms such as “installment.” For a UK audience, “instalment” is the usual spelling. The brand names stay the same.
Which One Should You Use?
For US Shoppers
Compare the available plans, total repayment amount, interest rate, and fees. Affirm may suit you if you want a longer monthly plan with clear interest terms. Klarna may suit you if you prefer its shopping tools or an eligible Pay in 4 offer.
For UK Shoppers
Check which service is available at your chosen store. Klarna may offer Pay in 3 or other local options. Do not assume that every US feature is available in the UK.
For Global Shoppers
First, check whether the service supports your country. Then compare the terms at checkout. If neither service is available, look for a local payment option.
My advice: Do not choose a service just because its name is popular. Choose the plan you can afford to repay on time.
Common Mistakes
Here are common mistakes people make when using Affirm or Klarna.
1. Thinking every plan is interest-free. Correction: Check the interest rate and total repayment amount before accepting a plan.
2. Assuming approval is guaranteed. Correction: Both services can decline a purchase.
3. Ignoring payment dates. Correction: Add every due date to your calendar.
4. Thinking late fees are always the same. Correction: Read the rules for your exact plan and country.
5. Using both services without a budget. Correction: Add up all your monthly and two-week payments before shopping.
6. Confusing the brands with ordinary credit cards. Correction: These services offer payment plans, but their terms differ from standard credit cards.
7. Assuming the services work in Pakistan. Correction: Check official country eligibility before signing up. Do not assume that a website accepting international orders also supports these payment services.
Everyday Usage Examples
Affirm and Klarna are brand names. You can use them in emails, social media posts, news reports, and formal writing.
In Emails
- “Can I use Affirm to pay for this laptop?”
- “Does your store accept Klarna?”
On Social Media
- “I am comparing Affirm and Klarna before buying a new phone.”
- “Always check the payment terms before using a Buy Now, Pay Later service.”
In News
- “Affirm expanded its payment options for eligible shoppers.”
- “Klarna introduced new payment features in selected markets.”
In Formal Writing
- “This report compares the payment plans offered by Affirm and Klarna.”
These examples show how both brand names fit into everyday English.
Usage Trends
Buy Now, Pay Later services have become a common part of online shopping. They let eligible shoppers divide a purchase into smaller payments instead of paying the full price at once.
Affirm and Klarna both serve this market. Their features continue to change as they add payment options and work with more stores.
Klarna was founded in Sweden, while Affirm began in the United States. Both now serve customers in multiple markets, subject to local availability.
However, popularity does not mean that either service is right for every shopper. Before choosing one, check the current terms and make sure the payments fit your budget.
Metaphors and Similes
Affirm and Klarna are brand names, so they do not have standard metaphorical meanings in English. However, writers can use comparisons to explain how these services work.
Metaphors
- “Small steps toward a big purchase.” This describes paying for an item in installments.
- “A bridge between buying and paying.” This describes the time between receiving a purchase and completing payment.
Similes
- “An installment plan can feel like climbing stairs one step at a time.”
- “A payment schedule is like a road map for your money.”
These are creative comparisons, not official descriptions of either company.
Connotative Meaning
The connotative meaning of a word is the feeling or idea it brings to mind. Affirm and Klarna are brand names, but people may connect them with different feelings.
Positive Meaning
Some shoppers may connect these services with ease and flexibility.
Examples:
- “Affirm helped me plan my payments.”
- “Klarna gave me another way to pay for my order.”
Negative Meaning
Other shoppers may connect Buy Now, Pay Later services with debt or spending too much.
Examples:
- “I used too many payment plans and lost track of my bills.”
- “Small payments made the purchase seem cheaper than it was.”
Neutral Meaning
In neutral writing, the names simply identify the services.
Examples:
- “The customer compared Affirm and Klarna.”
- “The report reviewed both payment services.”
The meaning depends on the context and the user’s experience.
Idioms and Proverbs
There are no widely established English idioms that specifically use the brand names Affirm or Klarna. However, common sayings about money can help explain their use.
1. Live Within Your Means
Meaning: Spend only what you can afford.
Example: “Before using Affirm or Klarna, live within your means.”
2. Look Before You Leap
Meaning: Think carefully before making a choice.
Example: “Look before you leap and compare the payment terms.”
3. A Penny Saved Is a Penny Earned
Meaning: Saving money is valuable.
Example: “Compare the total cost of both plans. A penny saved is a penny earned.”
4. Don’t Count Your Chickens Before They Hatch
Meaning: Do not assume something will happen before it is certain.
Example: “Do not plan a purchase around a payment plan until the service approves it.”
These sayings encourage careful spending.
Literature and Movies
Affirm and Klarna are financial service brands, not characters from famous books or films. There is no well-known classic literary work or major movie that defines the difference between them.
However, books and films about money, shopping, and consumer choices can help readers understand the ideas behind Buy Now, Pay Later services.
Literature
- The Psychology of Money — Morgan Housel (2020): A nonfiction book about money habits, choices, and financial behavior.
- The Richest Man in Babylon — George S. Clason (1926): A personal finance book that teaches saving and managing money.
Movies
- Confessions of a Shopaholic (2009, United States): A comedy about shopping habits and money problems.
- The Big Short (2015, United States): A drama about the financial crisis and risky lending.
These works do not focus on Affirm or Klarna. They provide broader lessons about spending, borrowing, and financial decisions.
Why This Difference Matters
A small payment may look easy to manage. But several small payments can add up quickly. Some plans are interest-free, while others may cost more than the original price.
Knowing how the two services work helps shoppers ask better questions:
- What is the full amount I will repay?
- Is there any interest?
- Are there late fees?
- When is each payment due?
- Can I afford the payments along with my other bills?
This knowledge also helps English learners understand financial articles and online shopping terms.
For businesses, clear payment information can help customers make informed choices. For society, better financial knowledge can reduce confusion about borrowing and spending.
Usefulness in Daily Life
Affirm and Klarna may be useful when you need to manage the cost of an eligible purchase.
For example, you may want to buy a computer for work or a washing machine for your home. A payment plan could spread the cost over time.
Here are practical ways to use these services wisely:
- Compare the full repayment amount before choosing.
- Check whether interest applies.
- Make sure the payment dates fit your income.
- Keep track of every active payment plan.
- Avoid borrowing for things you do not really need.
- Keep enough money for food, rent, bills, and emergencies.
Remember, splitting a payment does not make the item cheaper. It only changes when you pay for it.
Situational Preference
The better service depends on your needs. For a larger purchase, compare the monthly payment, interest rate, and total cost offered by Affirm and Klarna. For a smaller purchase, an eligible interest-free plan from either service may work well. If you want to avoid late fees, Affirm’s stated no-late-fee policy may be appealing, while Klarna’s terms should be checked for the specific product. If you shop often at stores that offer Klarna, its app may be convenient. Always compare the actual offer, not just the brand.
Possible asked questions
1. Is Affirm better than Klarna?
Neither is always better. Compare the payment plans, interest, fees, and approval terms for your purchase.
2. Is Affirm interest-free?
Some Affirm plans are interest-free. Other plans may charge interest, so check the terms before accepting an offer.
3. Is Klarna interest-free?
Klarna offers interest-free options, such as Pay in 4 in the US, when available and when the terms are met. Some longer financing plans may charge interest.
4. Which service has late fees?
Affirm says it does not charge late fees. Klarna may charge late fees on certain plans. Check the rules that apply to your purchase.
5. Can I use Affirm and Klarna at the same time?
You may be able to use both services if you qualify and the stores accept them. However, using both can make it harder to manage your payments. Make sure you can afford all your bills.
6. Do Affirm and Klarna check credit?
Credit checks and other approval checks depend on the service, payment product, and market. Read the relevant terms before applying.
7. Can I use Affirm or Klarna in Pakistan?
Do not assume either service is available to residents of Pakistan. Check the official websites for current country eligibility and account requirements before trying to sign up.
Conclusion
Affirm and Klarna are two well-known Buy Now, Pay Later services. Both help eligible shoppers spread the cost of certain purchases over time. However, they offer different plans, features, and terms.
Affirm may be a good choice if you want a clear monthly payment plan or want to avoid late fees under its stated policy. Klarna may suit you if you prefer its shopping app, want to pay later, or find an interest-free installment plan at a store you use. Neither service is always the cheapest or best option.
When comparing Affirm or Klarna, look beyond the size of each payment. Check the interest rate, total repayment amount, payment dates, late-fee rules, and approval terms. Also, make sure the service is available in your country.
Most importantly, remember that smaller payments do not mean a lower purchase price. A payment plan is useful only when you can afford it without missing other important bills.
The final choice: Compare the actual offers and choose the one that meets your needs at the lowest affordable total cost. If neither option fits your budget, consider waiting and saving the money first.


2 thoughts on “Affirm or Klarna: Which Buy Now, Pay Later Service Is Better?”